
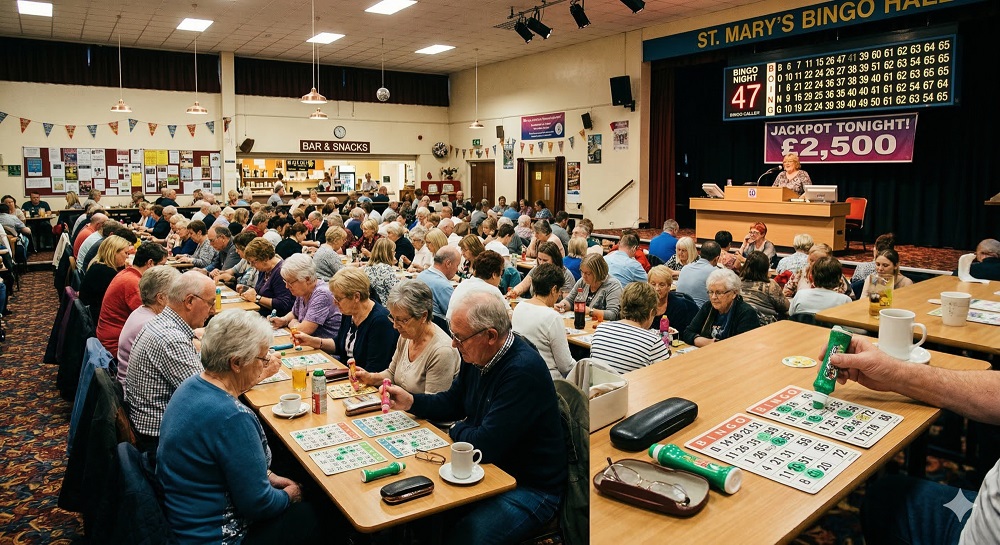
Stepping into a bustling bingo hall on a Friday night is a beloved American pastime, combining social camaraderie with the thrill of waiting for that final number to complete a coverall. When the caller announces your combination and you shout that winning word, collecting a crisp stack of cash feels like pure reward. What many regular players discover only at tax time, however, is that Uncle Sam views every dollar won at the bingo hall through the same lens as payouts from slot machines, poker tables, or the state lottery.
Under United States tax law, all gambling winnings represent fully taxable income. If you hit a substantial prize or several modest jackpots throughout the year, the Internal Revenue Service expects those amounts to appear on your federal income tax return. The good news is that federal tax statutes permit players to offset those winnings with legitimate losses incurred during the same calendar year. The catch is that deducting losses requires strict adherence to specific filing methods and rigorous recordkeeping standards. Failing to understand these mechanics can leave you with an unexpected tax bill on winnings you long since spent on subsequent buy-ins.
Understanding How the IRS Classifies Bingo Income
Before you can deduct a single dollar of bingo losses, you must understand how your winnings enter the federal tax equation. The tax code makes no allowance for casual hobbyists to simply tally their net profit or loss at the end of the year and report the bottom-line difference. If you won $4,000 over the course of twelve months but spent $5,000 on admission packs, paper sheets, and electronic machine rentals, you cannot simply report zero income or deduct a $1,000 net loss against your salary or pension.
Federal rules require casual players to report gross gambling winnings on their tax return, regardless of how much they spent to secure those wins. For the vast majority of players, this income is reported on Schedule 1 of Form 1040 under other income. Every prize, whether paid in cash, check, or merchandise, must be accounted for at its fair market value.
The threshold for official tax reporting at the hall itself often confuses players. Under federal law, a bingo hall operator must furnish Form W-2G to both the player and the government whenever a single payout reaches $1,200 or more, without deducting the wager. If you win an $800 jackpot, the hall will not generate a W-2G, but you remain legally obligated to report that $800 on your tax return. The tax liability exists because the income was realized, not because an informational tax document was printed.
The Mechanics of Deducting Losses on Schedule A
To deduct what you spent at the bingo hall, you must use Schedule A (Itemized Deductions). Gambling losses are classified as other itemized deductions and are entered on the designated line of this schedule. This structural requirement introduces the primary hurdle for casual players: you can only deduct your bingo losses if you itemize your deductions rather than taking the standard deduction.
Following major tax reforms, the standard deduction amounts for individuals, heads of household, and married couples filing jointly sit at historically elevated levels. Consequently, most American taxpayers take the standard deduction because their collective mortgage interest, charitable gifts, and state and local taxes do not exceed that baseline threshold.
If your total itemized deductions, including your verifiable bingo losses, remain lower than your allowable standard deduction, claiming those losses provides no financial benefit. In that scenario, you must still report the full amount of your gross winnings as taxable income on Schedule 1, which directly inflates your Adjusted Gross Income (AGI). An elevated AGI can trigger secondary tax consequences, such as phasing out specific credits or increasing the taxable portion of your Social Security benefits, even if you never actually profited at the tables.
Furthermore, the tax code imposes an absolute ceiling on gambling loss deductions: losses can never exceed reported winnings in any given tax year. If you report $3,000 in gross bingo winnings, your allowable deduction for losses is strictly capped at $3,000. You cannot carry forward unused losses into future tax years, nor can you use excess bingo expenses to offset wage earnings, investment gains, or retirement distributions.
Tracking by the Session Method
A frequent question among regular hall attendees is whether every individual card purchase counts as a separate transaction. Tracking every ninety-second game across a three-hour session is impractical and does not reflect how players purchase their games. Tax authorities recognize what is known as the session method for tracking gambling activity.
Under the session method, a player measures their net financial outcome at the conclusion of a distinct, continuous gambling period rather than on a per-card or per-game basis. For a bingo player, a session typically corresponds to an organized program run by the venue, such as an early-bird session, a main evening program, or a midnight special.
To apply this method correctly, you record the total cost of participating in that specific session and compare it against the total payouts received during the same block of time.
What Belongs in Session Costs
Calculating your cost basis for a session involves aggregating all direct out-of-pocket expenses tied to playing the games on that occasion:
-
Admission fees and entry packs required to sit at the table
-
Additional paper packages, floor specials, and coverall sheets
-
Computer terminal or electronic handheld machine rental fees
-
Pull-tab cards and instant-win tickets purchased on the floor during the session
Ancillary expenditures do not qualify as deductible gambling losses. The IRS strictly disallows personal living and entertainment expenses incurred around the activity. Money spent on snacks at the concession stand, travel costs driving to the hall, parking fees, and voluntary tips handed to floor workers or callers cannot be added to your session costs.
Calculating Net Results for the Day
If you attend a Sunday afternoon program, spend $120 on an electronic unit loaded with cards, buy $30 of floor specials, and win a $200 game midway through the session, your net result for that session is a $50 gain. That $50 represents gross winning income for that session.
Conversely, if you purchase $150 worth of packs and leave the hall without calling a single valid bingo, your session result is a $150 loss. That $150 enters your cumulative loss column. Under the session approach, you accumulate all positive session totals to arrive at your annual gross winnings, while accumulating all negative session totals to calculate your deductible losses on Schedule A, up to the ceiling of those winnings.
Building an Audit-Proof Paper Trail
The IRS views gambling loss deductions with heightened scrutiny. During an audit, examiners routinely disallow deductions backed solely by memory, rough estimates, or generic bank withdrawals. If you claim thousands of dollars in bingo losses, you must establish an organized, contemporary paper trail that corroborates every dollar deducted.
The foundational pillar of your defense is a contemporaneous log or diary. The word contemporaneous is vital: entries must be recorded at or near the time of play, not reconstructed months later when preparing your tax return.
For every visit to the hall, your log should clearly capture the following details:
-
The exact date and specific time window of the session
-
The legal name and physical address of the bingo facility or charitable organization hosting the event
-
The specific types of games played, such as paper specials, electronic games, or pull-tabs
-
The total dollar amount wagered, representing your buy-ins and add-on packs
-
The total dollar amount won, including small split pots and major jackpots
-
The table number or electronic terminal identifier, if assigned
In addition to your written or digital log, you must retain secondary corroborating documentation. Save your dated admission receipts, paper game receipts, and cashier slips. If you pay for buy-ins using personal checks or debit cards, keep the corresponding bank statements that tie directly to the hall’s merchant account.
Many players collect losing paper sheets, hoping a trunk full of discarded cards will satisfy an auditor. Tax courts have repeatedly held that an unorganized collection of losing cards carries little evidentiary weight on its own, because cards can easily be picked up off floor tables or gathered from fellow players after a session ends. However, when dated losing sheets directly match the entries, dates, and expenditure figures in your detailed diary, they transform into valuable supporting evidence.
State-Level Tax Nuances That Catch Players Off Guard
While federal guidelines provide a uniform standard across the country, state income tax treatment introduces significant complexity. Many states follow federal adjusted gross income as their starting baseline for calculating state tax liability, but they diverge widely on whether they allow itemized deductions for gambling losses.
Several states require taxpayers to add back their gross gambling winnings to their state income calculation while outright prohibiting any deduction for gambling losses on the state return. In these jurisdictions, a resident who wins $10,000 in gross bingo payouts and loses $10,000 in the same halls will break even financially, deduct the loss on their federal Schedule A, but still face a state income tax assessment on the full $10,000 of winnings.
Other states permit deductions only up to a restricted percentage or disallow them unless the taxpayer meets narrow professional criteria. Before assuming your federal deductions will protect you at the state level, review the specific personal income tax statutes in your home state to determine how local revenue agencies handle gaming income and offsetting losses.
Structuring Your Bingo Play for Tax Compliance
Maintaining compliance does not require abandoning the enjoyment of the game, but it does demand a structured approach for players who attend halls regularly.
Establish a dedicated bank account or separate debit card specifically designated for your recreation fund. Drawing buy-in funds from a single account creates an unbroken, digital trail of cash outflows that corresponds directly to the dates recorded in your personal log. Avoid relying exclusively on untracked cash drawn from automated teller machines, which creates ambiguous records that fail to show where the cash was ultimately spent.
Take two minutes at the conclusion of every session, before leaving the hall parking lot, to record your numbers in your log. Entering your costs and returns immediately ensures accuracy, eliminates guesswork, and creates a defensible record that satisfies tax authorities.
Treating your bingo expenditures with accounting discipline protects your hard-earned winnings. By understanding the limitations of Schedule A, applying the session method correctly, and maintaining an unimpeachable ledger, you can participate in your local hall with full confidence that your tax filings remain secure, legal, and audit-ready.

Comments are closed.